
How lifestyle funds work
Lifestyle funds are often used as the default option in workplace pension schemes. If your employer chose a lifestyle fund as your scheme's default option, you'll have been automatically invested in it when you joined. This means your pension savings started being invested straight away, without you needing to make an investment decision.
When you are further from retirement, your money is invested in a mix of investments aimed at helping your savings grow over the long term. As you get closer to your target retirement age, typically around six to seven years before you plan to retire, although this may vary, the fund gradually and automatically changes where your savings are invested. This is designed to support one of three retirement options:
Flexible
If you want to keep your income options open
Annuity
If you plan to buy a guaranteed income
Cash
If you plan to take your savings as cash
The value of investments can go down as well as up and isn't guaranteed. You may get back less than you invest.

It’s important to check that your fund is invested in a way that supports how you plan to take your retirement savings. If it isn’t, your savings could gradually move into investments that may not match your plans, which could affect how much you have when you retire.
Log in to view your fund factsheet and check the retirement option your fund is targeting.
Main types of lifestyle fund
There are three main types of lifestyle fund. You can learn how each type works by selecting the tabs below:
For those who want to keep their options open
How it works

Growth stage - when retirement is still some way off
Your money is invested in a diversified mix of investments designed to grow your pension savings over the long-term.
The exact mix, the level of growth potential and investment risk, will depend on which fund you’re invested in. You can find out more in the fund objective at the top of each fund's factsheet.

Retirement target stage – as retirement nears
As you get closer to your target retirement date, usually around six or seven years before (though this can vary), your savings are gradually and automatically moved into less risky investments, helping to reduce exposure to market ups and downs while retaining some potential for them to grow.
This approach recognises that market falls shortly before you retire can have a big impact on the amount of income you'll be able to take. So there's a greater focus on preserving the savings you've built up, although they could still fall. Your fund remains spread across a wide mix of investments, so you're not reliant on the success or otherwise of just one type.
Some Flexible Target funds will also move up to 25% of your savings into cash to cater for your tax-free allowance¹.
During the retirement target stage, your fund name will change to include your target retirement year, making it easier to identify the fund that matches your chosen retirement date.
Here's an example of how the fund changes in the years before you retire:
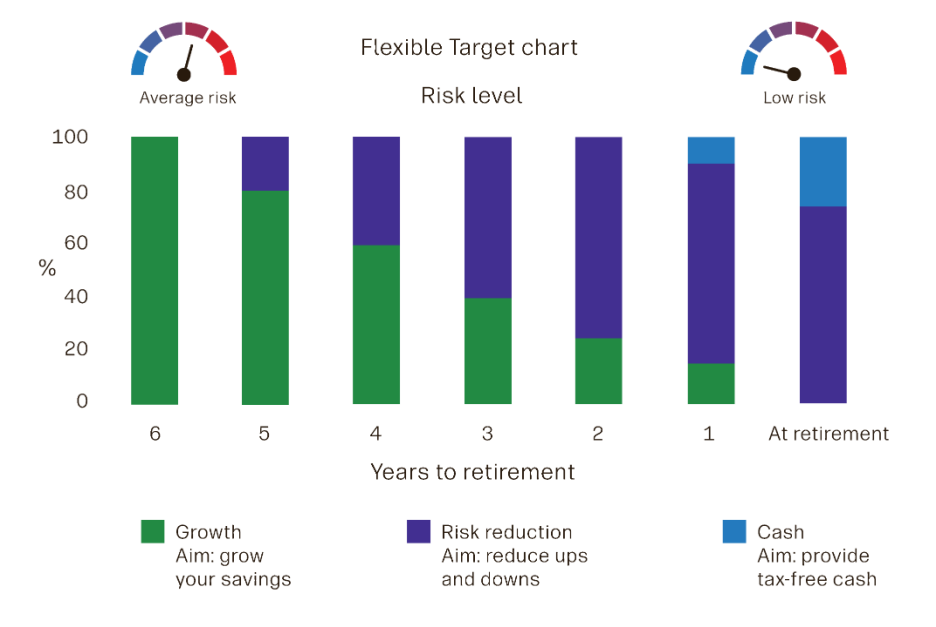
This is an example only. Some funds start at different risk levels and move into less risky investments and cash at different times. Some funds don't move into cash.
Risk levels are set by Aegon and shouldn’t be compared with those used by other providers.

At retirement – when you’re ready to access your savings
When you reach your target retirement age, your savings move into a cautious, diversified mix of investments, giving them the continued opportunity to grow and support a retirement income, although they may also fall.
You can choose to stay invested and drawdown an income, buy an annuity, take cash, or a combination. Your options remain open.
The value of investments in all stages of the lifestyle fund process may go down as well as up and you may get back less than you invest.
1 You can currently take up to 25% of your pension savings as tax-free cash. This is based on our understanding of current taxation law and HMRC practice, which may change.
For those who plan to buy a guaranteed annuity income
How it works

Growth stage - when retirement is still some way off
Your money is invested in a diversified mix of investments designed to grow your pension savings over the long-term.
The exact mix, the level of growth potential and investment risk, will depend on which fund you’re invested in. You can find out more in the fund objective at the top of each fund's factsheet.

Retirement target stage – as retirement nears
As you get closer to your target retirement age, usually around six or seven years before (though this can vary), your fund gradually and automatically moves into investments designed to prepare you for buying an annuity. These investments aim to broadly offset changes in annuity prices.
This includes bonds, which are loans to governments or companies, including a significant amount in long-dated UK government bonds, also known as long gilts.
Long gilts and annuity rates often move in opposite directions. This means that when one goes up, the other may fall, although this won’t always happen. The aim is to give you more certainty about the level of annuity you may be able to buy when you retire.
The fund will also move 25% of your savings into cash to cater for your tax-free cash entitlement2.
During the retirement target stage, your fund name will change to include your target retirement year, making it easier to identify the fund that matches your chosen retirement date.
Here's an example of how the fund changes in the years before you retire:
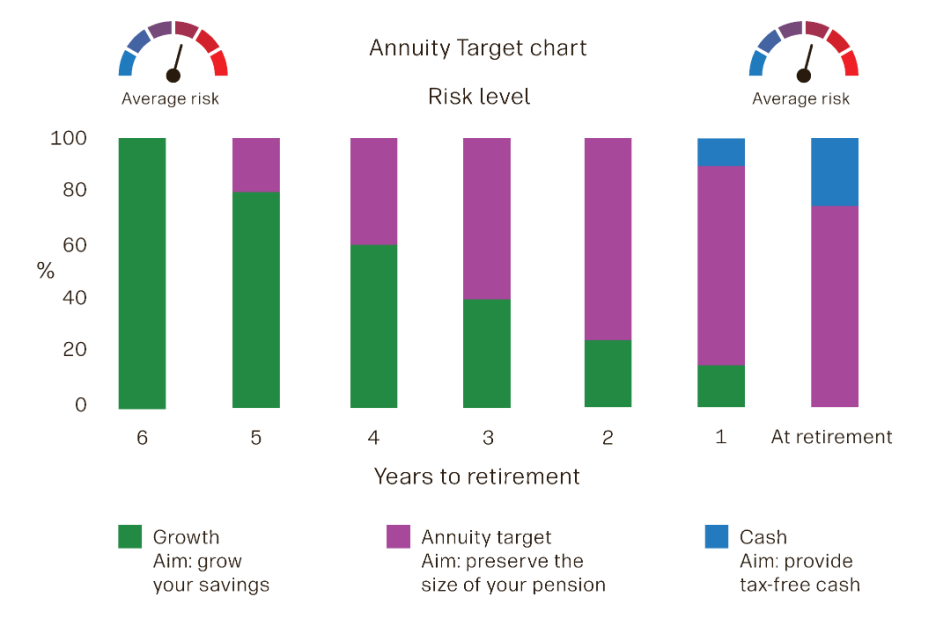
This is an example only. Some lifestyle funds start and end at different risk levels and move into investments designed to protect your annuity buying power and cash at different times.
Risk levels are set by Aegon and shouldn’t be compared with those used by other providers.
This type of fund could limit how much your savings grow. Because your savings are gradually moved into fewer types of investments, they could also be more affected if those investments fall in value.
When this fund was created, many people used their pension savings to buy an annuity, so it was designed with that option in mind. Since then, more retirement income options have become available. Today, around 1 in 10 pensions are used to buy an annuity at retirement³.
If you’re currently invested in an annuity target fund, it’s important to check whether it still matches your retirment plans.

At retirement – when you’re ready to access your savings
When you reach your target retirement age, your savings will hold 75% in bonds and 25% cash, ready for you to buy an annuity and take some tax-free cash.
This investment mix isn't designed for long-term investing as returns are unlikely to keep pace with inflation, eroding the value of your savings over time.
The value of investments in all stages of the lifestyle fund process may go down as well as up and you may get back less than you invest. When you buy an annuity, you’ll normally need to shop around and speak to a financial adviser to get the best deal.
2 You can currently take up to 25% of your pension savings as tax-free cash. This is based on our understanding of current taxation law and HMRC practice, which may change.
3 Source: Financial Conduct Authority, Retirement income market data 2024/25.
For those who plan to take their savings as cash
Please note, the only Cash Target fund available is the Growth Tracker (Cash Target) fund.
How it works

Growth stage - when retirement is still some way off
Your money is invested mainly in UK and international equities (company shares), with the remainder in bonds (loans to governments or companies) and/or cash. The fund is designed to track the markets it invests in, so its performance will broadly follow those markets, though there’s no guarantee, and its value can fall as well as rise.

Retirement target stage – as retirement nears
As you get closer to your target retirement age, around six years before, your fund gradually and automatically moves into investments that are generally considered to be less risky.
In the final three years before your selected retirement age, your savings are then moved into cash, ready for you to take your benefits.
During the retirement target stage, your fund name will change to include your target retirement year, making it easier to identify the fund that matches your chosen retirement date.
Here's an example of how the fund changes in the years before you retire:

Risk levels are set by Aegon and shouldn’t be compared with those used by other providers.

At retirement – when you’re ready to access your savings
When you reach your target retirement age, your savings move into cash and stay there until you tell us what you’d like to do. You can take 25% of your savings tax-free4 with any further withdrawals subject to income tax.
Cash isn't well-suited to long-term investing. Inflation can gradually reduce the spending power of your savings, meaning each pound buys a little less over time.
The value of investments in all stages of the lifestyle fund process may go down as well as up and you may get back less than you invest.
4 You can currently take up to 25% of your pension savings as tax-free cash. This is based on our understanding of current taxation law and HMRC practice, which may change.